You already know your BAH. You see it on your LES every month. What most service members haven't run the numbers on is how much house that allowance actually unlocks once a lender treats it as income — and that number is what really decides where you can buy at Fort Carson, Peterson SFB, or Schriever SFB.
I've been through multiple PCS moves with my own family, so I know the first real question isn't "what's my rate" — it's "what can I actually get into here." Let's answer that.
How Your Bah Drives Your Preapproval
Your housing allowance isn't just rent money. On a VA loan, it does three things that directly raise the price you qualify for.
It counts as income. Lenders add your BAH to your base pay when they calculate what you can afford. It's not a side note — for most ranks it's the single biggest piece of your qualifying income after base pay.
It gets grossed up. Because BAH is tax-free, most lenders treat it as worth more than its face value — commonly around 25% more — to reflect that you keep all of it. A $2,358 BAH check can qualify like roughly $2,950 of taxable income. That bump alone moves your price ceiling.
It stacks instead of splitting. On a VA loan there's no down payment to save for and no monthly PMI. So your BAH isn't getting divided between a savings goal and a payment — the whole allowance is available to support a mortgage.
Put those together and the same allowance you'd hand a landlord becomes the engine behind your preapproval.
What Each Rank Can Get Preapproved for in Colorado Springs
Here's the part worth screenshotting. The table below shows a realistic target purchase price by rank, using a VA loan with $0 down, 2026 Colorado Springs BAH at the with-dependents rate, base pay at a typical time-in-service for that rank, and a buyer with good credit, low debt, and a clean payment history.
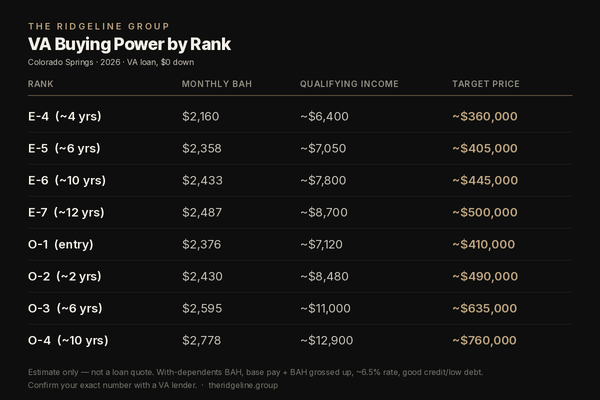
*Combined qualifying income = base pay plus BAH grossed up for being tax-free. BAS and special pays would push it higher — these figures are intentionally conservative.
A few things to read correctly:
These are ballparks, not a loan quote. Your real preapproval comes from a lender pulling your credit and your LES. The point of this table is to show how much your rank and allowance move the ceiling — not to lock in a number.
The Colorado Springs median home price is sitting around $385,000–$420,000. So an E-5 with dependents is right at the median, and most ranks above that have real room to choose neighborhoods, not just settle.
Single service members qualify for less. The without-dependents BAH runs a few hundred dollars lower, which trims roughly $35,000–$45,000 off the target prices above.
What Moves Your Number up or Down
The table assumes a clean financial picture. Here's what shifts it in the real world.
Debt is the biggest lever. A $450 car payment doesn't just cost you $450 — it can knock $60,000–$70,000 off your price ceiling, because lenders count it against the same income your housing payment draws from. Paying down a card or holding off on a new truck before you buy is often worth more than any rate shopping.
Credit score changes your rate, and your rate changes your price. The gap between a 740 and a 620 score can be a couple hundred dollars a month on the same loan — which is real purchasing power gained or lost.
Rates move daily. I ran these numbers at roughly 6.5%, which is where 30-year VA rates have been hovering in 2026. If rates drop, every rank's ceiling rises; if they climb, it tightens. Don't anchor to a number you saw three months ago.
Why the VA Loan Makes Your Bah Go Further
This is the part that separates a military buyer from a civilian one. A VA loan means no down payment and no monthly mortgage insurance. A civilian putting 5% down on a $400,000 home needs $20,000 in cash plus PMI eating into the payment. You need neither.
That's why your BAH stretches further than the same dollar amount would for a civilian neighbor — none of it is getting siphoned off to cover PMI or rebuild a down-payment fund. It goes straight to principal, interest, taxes, and insurance on a home you own.
Before You Get Attached to a Price
One honest caveat, because I'd rather say it now than watch it cost you later: the math changes with how long you're here.
On a tour of two years or less, buying and selling costs (6–8% of the home's value) usually wipe out any equity you'd build, and renting is the smarter move. At three years you're at break-even — buying makes sense especially if you'd keep the place as a rental when you PCS out, and Colorado Springs has a strong military rental market for exactly that. Three-plus years or planning to stay, owning tends to win clearly.
The preapproval number tells you what you can buy. Your orders tell you whether you should. Both matter.
How to Confirm Your Real Number
Use this table to house-hunt smart, then nail down the actual figure:
- Confirm your exact BAH on the official DoD BAH Rate Lookup — enter your duty station ZIP, pay grade, and dependency status.
- Get preapproved with a lender who knows VA loans. This is the step that turns a ballpark into a real budget, and it's free. A good VA lender will gross up your BAH correctly and factor in your residual income, which is where VA loans are more flexible than conventional.
- If you're between bases during a PCS, ask finance about overlap rules — you may briefly draw BAH at two locations.
I can connect you with a lender who handles VA loans every week and won't waste your time. From there, we match the preapproval to the right neighborhoods for your timeline.
Bottom Line
Your BAH is the foundation of your buying power, not just your rent budget. On a VA loan it counts as income, gets grossed up for being tax-free, and goes to work with $0 down — which is why an E-5 with dependents can target the Colorado Springs median and most ranks above that have real room to choose.
Confirm your exact BAH, get preapproved, and weigh the buy decision against your tour length. If you want help running your actual number or figuring out where it goes furthest in town, reach out. No pressure — just answers.
Brandon Lecocq
- Phone: (719) 413-6610
- Email: [email protected]. Book a call
For the local market and military housing updates that matter, delivered weekly, sign up for The Ridgeline Rundown.