If you’re thinking about buying a home, one of the smartest first moves you can make in real estate is getting pre-approved for a home loan. It’s not the flashiest part of the process, but it’s one of the most important. Pre-approval gives you clarity on budget, strengthens your offer, and positions you as a serious buyer in a competitive market.
I like to explain pre-approval to clients as the foundation of the entire home-buying journey. Before we look at homes, before we write offers, we want to make sure the financing piece is dialed in so everything else moves smoothly.
Let’s break it down step-by-step so you know exactly what to expect.
What is a Mortgage Pre-approval and Why Does It Matter in Real Estate?
A mortgage pre-approval is a lender’s written estimate of how much you can borrow based on a review of your financial profile. It’s more in-depth than a pre-qualification and carries real weight when you start submitting offers.
Here’s why it matters:
- Defines your budget – You know your price range before shopping
- Strengthens your offer – Sellers take pre-approved buyers seriously
- Speeds up closing timelines – Financing is already vetted
- Identifies issues early – Credit, income, or debt concerns can be addressed upfront
In competitive real estate markets like Colorado Springs — especially around military relocations — pre-approval can be the difference between winning and losing a home.
If you’re relocating or using VA benefits, I always recommend working with a lender who understands military financing timelines and entitlements.
What Documents Do You Need to Get Pre-approved?
This is where preparation makes everything easier. Lenders are verifying your ability to repay the loan, so documentation is key.
Here’s what most lenders will ask for:
Income Verification
- Last 30 days of pay stubs
- Last 2 years of W-2s or 1099s
- Tax returns (if self-employed or commissioned)– all pages, schedules, and K-1s for the past 2 years
- If you own more than 25% of a business, you will likely need to provide business tax returns as well
Asset Statements
- Bank statements (2–3 months)
- Retirement or investment accounts
- Gift fund documentation (if applicable)
Employment History
- Employer contact information
- Two-year work history
Identification
- Driver’s license
- Social Security number (for credit pull)
If you’re active duty or a veteran, lenders may also request:
- Certificate of Eligibility (COE) for VA loans
- LES statements
Having these ready upfront speeds up the process significantly.
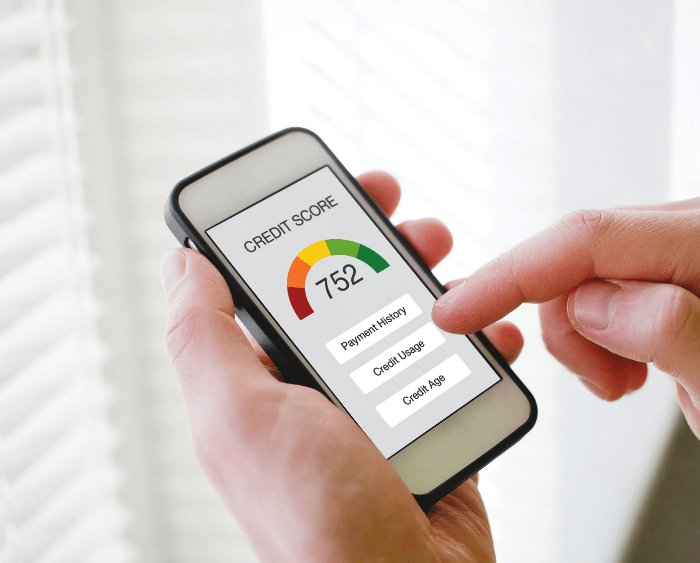
How Does Your Credit Score Impact Pre-approval?
Your credit score plays a major role in both approval and loan terms.
Here’s how lenders typically view scores:
- 740+ → Best rates and terms
- 700–739 → Strong financing options
- 640–699 → Still financeable, slightly higher rates
- Below 640 → May need credit improvement first
But credit isn’t just about the score — lenders also review:
- Payment history
- Credit utilization
- Length of credit history
- Recent inquiries
If your credit needs work, don’t stress. I’ve helped plenty of clients create a game plan to improve scores quickly.
Quick tips:
- Pay down credit cards
- Avoid new debt
- Don’t close old accounts
- Make on-time payments
How Much Home Can You Afford?
This is the question everyone wants answered — but affordability isn’t just about what you’re approved for.
Lenders calculate affordability using your debt-to-income ratio (DTI).
Front-end Ratio
Housing expenses ÷ gross income
Back-end Ratio
All debts ÷ gross income
Most lenders prefer:
- 28–31% front-end
- 43–50% back-end (loan dependent)
Gross vs. Net Income — What’s the Difference?
This is an important distinction.
Gross income is your income before taxes and deductions. Net income is what actually hits your bank account after taxes, insurance, retirement contributions, and other withholdings.
Lenders use gross income when calculating DTI. However, when we plan your budget, I like to look at your net income so we make sure your payment feels comfortable in real life — not just on paper.
But here’s my advice — just because you’re approved for a number doesn’t mean you should spend it.
We also factor in:
- Lifestyle goals
- PCS timelines
- Investment plans
- Family growth
A comfortable payment always beats a stretched one.
What’s the Difference between Pre-qualification and Pre-approval?
This gets confused a lot, so let’s simplify it.
Pre-qualification
- Self-reported finances
- No document verification
- Quick estimate only
Pre-approval
- Verified documents
- Credit pulled
- Underwriter reviewed
- Official approval letter issued
In real estate negotiations, only pre-approval holds weight.
If you’re writing an offer with me, I always recommend full pre-approval — not just pre-qualification — to put you in the strongest position possible.
How Long Does the Pre-approval Process Take?
Good news — it’s usually faster than people expect.
Typical timeline:
- Application: 30–60 minutes
- Document submission: 1–2 days
- Lender review: 1–3 days
- Pre-approval issued: 2–5 business days
If you’re highly organized, it can happen in under 48 hours.
Pre-approvals are usually valid for 60–90 days, though lenders can refresh them if home shopping takes longer.
What Mistakes Should You Avoid before and after Pre-approval?
This is a big one. Once you’re pre-approved, your financial profile needs to stay stable until closing.
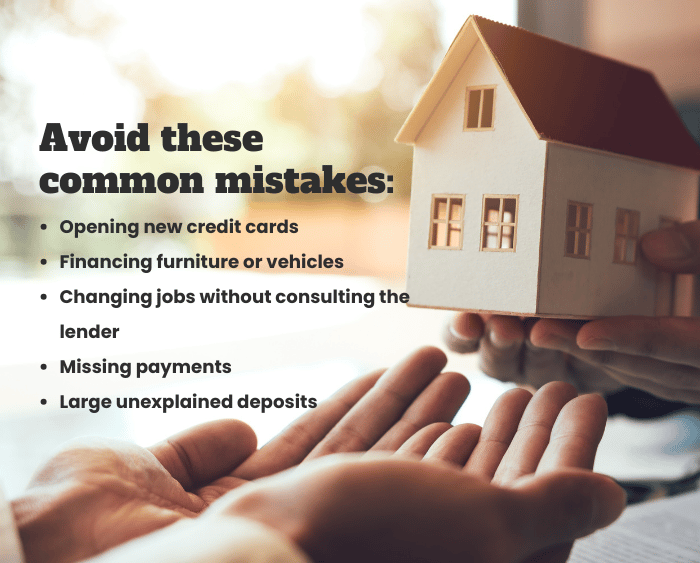
I always tell clients: If it impacts your credit or bank account, talk to your lender first.
It’s much easier to prevent issues than fix them under contract.
How Pre-approval Strengthens Your Offer
From a seller’s perspective, pre-approval reduces risk.
It tells them:
- Financing is vetted
- Buyer is serious
- Closing is more likely
In competitive real estate scenarios, we can pair pre-approval with:
- Strong earnest money
- Flexible closing timelines
- Clean contract terms
All of this works together to make your offer stand out.
Key Takeaways: Pre-approval Made Simple
If you remember nothing else, remember this:
- Pre-approval is step one in smart real estate planning
- It defines budget and strengthens offers
- Documentation readiness speeds everything up
- Credit and DTI drive loan terms
- Financial stability must continue through closing
Getting pre-approved early removes stress, creates clarity, and allows you to shop with confidence instead of guesswork.
Let’s Talk Strategy
If you’re thinking about buying — whether it’s next month or next year — I’m always happy to walk you through the pre-approval process and connect you with lenders who align with your goals.
- 📞 Phone: (719) 413-6610
- 📩 Email: [email protected]
No pressure — just a conversation so you can make informed decisions.